No Bullsh*t Talks · Season 3 · Episode 4
The Truth About Raising Money – What Founders Get Wrong
With Anthony Rose.
 Watch on YouTube
 Listen on Spotify
 Apple Podcasts
About this conversation
On Fundraising and Investors
In this episode of No Bullsh* t Talks , I sit down with Anthony Rose , CEO of SeedLegals , to uncover the truth about raising capital. From pitching to term sheets, Anthony shares the real mistakes founders make when trying to secure funding — and what separates successful raises from failed ones. Whether you’re raising your first round or preparing for Series A, this episode is packed with unfiltered advice and insider knowledge you won’t hear anywhere else.
🔑 In this episode: The most common fundraising mistakes What investors are really looking for How to stand out in a crowded pitch environment When to raise, how much, and who to target The BS that founders need to stop believing 🔥 If you’re thinking of raising money — WATCH THIS FIRST.
Watch
See the full video conversation.
Listen
Take the conversation with you.
 Audible
Watch the moments
that travelled.
Watch, share and continue on the original platform.
Read the full conversation.
The transcript is organised by timestamp so it can be generated from the master transcript, edited once, and published here without designing a new section every week.
Trailer+
I’m in the business of helping people get funded.
You know, fundraising is really the failure to build a business without needing funding.
So, let’s go through the beginning.
SeedLegals’ data shows that founders invest a median of £26,000 of their own money into the business before they raise investment.
So, that’s the bootstrapping part.
An investor won’t invest just on a PowerPoint.
You have to build something.
The problem is, now you need to get a developer, a designer, and a product person, and you can’t afford it yourself.
So, the time to get investment is when your ability to fund the business yourself is limiting its growth.
Intro to No Bullsh*t Talks+
No Bullsh*t Talks is a podcast for entrepreneurs, by entrepreneurs.
There’s too much bullshit out there, especially when it comes to business.
This podcast aims to highlight what’s true and what’s not in the world of entrepreneurship, bringing you honest and raw conversations about the roller coaster that is entrepreneurship.
Each week, my guest will be a high-performing entrepreneur, sharing the ups and downs of their journey and helping you prepare for the road ahead while providing you with actionable insights and absolute gems of knowledge.
Stay tuned as I introduce this week’s guest.
Intro to Anthony Rose+
Anthony Rose is the founder and CEO of Seed Legals, the platform to join as a startup looking to raise capital.
He’s the man behind the launch of BBC iPlayer, but as a serial entrepreneur at heart, he created a solution to the problems that he found frustrating as a founder.
He’s helped over 50,000 startups get funded and has completely changed the way legal agreements are handled in startups.
I present to you this week’s guest, Anthony Rose.
Founding SeedLegals+
Welcome, Anthony, to No Bullsh*t Talks.
Hello.
Thank you.
Thank you so much for being here.
I’m super excited to have you because not only are you an entrepreneur in your own right, you are helping entrepreneurs and helping them grow their businesses.
And I just think that that’s going to make this the most insightful episode.
I’ve got so many different questions to ask you.
I’m looking forward to giving it a go.
I know.
So, I would love for you to just introduce yourself a little bit and explain to everyone what you do.
All right.
So, I’m Anthony.
I’m founder and CEO at Seed Legals.
Years ago, I used to head up BBC iPlayer.
Then I left, built a startup, sold it, built another startup, sold it, and invested in a few.
I got tired of paying lawyers.
I met my co-founder, Laar Lafi, a genius ex-VC and serial angel investor, and we got together to create Seed Legals so other founders don’t have to pay lots of money to lawyers.
We’re 160 people.
Around 50,000 UK companies are on Seed Legals.
Most UK startups are on Seed Legals.
About a third of all early-stage fundraising in the UK goes through our platform.
So, I talk to thousands of founders, and I’m here to share any experiences, wisdom, and so on that I’ve gained over the years or from talking to lots of founders.
Ah, it’s so amazing.
Like, I can’t believe how many founders are on the platform.
But it’s actually just a no-brainer, right?
Because, like you said, I think the best companies are founded out of a personal gripe that you find.
Like you said, you were sick of paying all these lawyers.
As a startup, you quite often don’t have the thousands of pounds to pay these legal fees, so you started the company.
What was the moment like when you realized that this could be a thing?
Well, obviously, one of the nice things as a founder is if you use your own platform, right?
If you eat your own food or ride your own bicycle.
In our case, we’re doing our own funding rounds and running our team on our platform.
So, all of our employment agreements and all of our share option schemes are on it.
But one of the things I realized when we created Seed Legals is that when you go to a lawyer, the product they give you is a legal document.
No one really cares about a legal document.
It’s a necessary thing, but what you really want as a founder is, “Help me find investors,” or, “How do I give them their SEIS?” or, “I’ve spoken to an investor. What do I do next?”
So, to me, ultimately, we realized it’s all about empowerment and a solution.
The solution is data to show you what’s market standard, so you’re not the only idiot in the room pushing back against an investor.
You can show them that 75% of the time, this is the way it goes, and so on.
It’s also videos to show you how to find investors and create a great pitch deck.
Then it’s an always-on platform.
It’s a billing model that doesn’t go by the hour.
And, importantly, it’s something that, when you find an investor, you know what to do next.
It’s all about removing those unknowns.
If you can just show people that there’s actually a standard formula, every startup idea is different, but the formula for UK startups is remarkably self-similar.
By productizing that, everything becomes like 100 times easier.
Should everyone get funding?+
Yeah, absolutely.
And I’ve got so many questions to ask. I don’t even know where to start.
I feel like the best place to start is, I guess, so many people talk about getting funded because, obviously, running a business is hard.
Where do you find the money?
It’s almost like a chicken-and-egg situation as well.
And so the natural thing people go, “Well, let’s go get money from somewhere.”
Is it always the right thing to do, that, for a start?
Because I think that people just assume, “I must go get funding.”
Like, what sort of businesses should go get funding?
Are there any that should try to bootstrap it?
And what are the downsides of getting funding?
Right, great question.
So, although I’m in the business of helping people get funded, fundraising is really the failure to build a business without needing funding.
So, let’s go through the beginning, which is SeedLegals’ data shows that founders invest a median of 26,000 of their own money into the business before they raise investment.
So, you know, that’s the bootstrapping part.
So, an investor won’t invest just on a PowerPoint.
You have to build something.
The problem is now you need to get a developer, and you need to get a designer, and you need to get a product person, and you can’t afford it yourself.
So, the time to get investment is the time when your ability to fund it yourself is limiting the growth of the business.
So, you know, your life has a value as well.
So, if you’re going to spend another two years kind of tinkering yourself and finding a co-founder, as opposed to getting someone else’s money to grow the business at 5x the rate, you’re far better off giving away some equity to do that.
So, the time to get funded is the point where the business, you’ve created enough value that the valuation is high enough that you can give away a modest amount of equity for the money you need.
So now, in terms of getting money, well, what are the sources?
You can go to Innovate UK, but the problem is the chance of most of those grants is tiny.
The Smart Grants, what people didn’t realize—the dirty secret—was it had less than a 2% success rate.
I mean, you can literally go to the casino, put your money on 26 red, and have a higher chance of getting money than from an Innovate UK Smart Grant.
So, they’ve ended that because it was insane.
So, the other thing is you can go to a bank.
And the bank is great because you don’t have to give away equity.
You don’t have anyone with shares in your business.
But the bank’s never going to lend you money because you don’t have revenue and profit to repay it.
Plus, you should never borrow money unless you can repay it.
Otherwise, you’re bankrupt.
So, getting a loan is generally out, which means equity investment.
So, someone gives you money, and you’re giving them shares in your business.
And here many founders go, “Great, you know, I’m going to dilute 15%.”
So, sell 15% on average in the business at each funding round, and I slowly have less control over the business, but the business is growing.
Some founders get paranoid.
“Oh my God, I’m going to give away something in the business.”
“I’m going to try hard to give nothing in the business.”
But I think that’s wrong because, again, think about the next five years of your life.
You want, at the end of five years, to have a business that’s worth tens of millions that you can have an exit.
If a part of that is to give away some of your business, you’re much better to have 50% of a 50 million business than 100% of something that you’re putting all your money into yourself, not being paid a salary, to then scrappily do everything yourself.
So, there’s a trade-off, right?
And what you want to do, and this is where SeedLegals comes in, is to set things up so you can sell equity in the business, but without giving away too much control.
We’ve all read stories of Sam Altman and OpenAI getting fired by the board.
Some founders go the other direction.
They want to make these super-voting shares so you can’t get rid of me.
Literally 100% of the time I’ve seen people do that, it has to get unwound later because investors hate that kind of thing.
Investors see lots of founders.
And this is really, ultimately, the single bit of advice, which is any VC fund or any serial angel investor sees lots of founders.
And if you fit the standard pattern, which is smart founders looking to change the world, you know, usually with the B2B SaaS model, which can scale quickly, focused on a big market opportunity and execution to get there rapidly, you’re in.
But as soon as you’re doing things that are weird, like, “I’ve made special super-voting shares for me,” or, “I’m a charity,” or whatever it might be, or, “I’ve got asset locks on the business,” it just goes into, “This is too hard. Next, please.”
And so you’re disadvantaging yourself.
Wow.
I mean, that’s so insightful to think because I think that is a thing that founders struggle with, is giving up control in general.
And I think the similarities are there when you’re employing people, right?
So, it’s the same sort of concept.
You’re saying, like, why stress all that, put all that energy in, when you know you’re going to be more profitable in a few years?
Same thing.
Why do everything yourself if you can delegate and you could hire someone?
But the lack of control, lack of giving away funds, it’s a difficult thing for a lot of founders.
I think it’s their baby.
It’s their thing.
But I think there’s a few things there that I’d love to touch on.
First of all, I thought it was amazing that you described getting funded as actually a failure, which I love because the narrative of funding is sort of like we are successful because we got this.
But actually you’re saying if you actually could do it yourself, that’s a better option in a way, right?
Well, of course, life is easier, but it’s not possible unless you’re independently wealthy.
Usually on your second or third exit, you’ve now got enough money to go and do your next startup yourself.
But, you know, you can’t own more than 100% of your own business.
So, at some point, it makes sense to not keep putting your money in.
Have someone else put their money in.
And, yeah, you grow the business faster.
The trick is to find the right level of control that you and your investors have.
And what I’ve learned at SeedLegals is funding, like all contracts over the years, over the decades, has developed into a sort of set of checks and balances between both parties.
The investors are paranoid that the founders own 80% of the shares in the business and can do whatever they want.
They could sell the business.
They could pivot to something else.
So, investors want some controls.
And founders are paranoid the investors will try and get rid of them.
But realistically, in the early stages of the business, the founders have got 80% of the shares.
They own the board.
They’ve got all the power.
And for the investor, the risk is that the company isn’t going to get to product-market fit and it’s going to go bankrupt.
So, founders don’t need to worry.
When you get to Series A level and you’ve had several rounds of dilution, at that point you may find that your equity is decreasing.
But the trick there is not to dilute too much in each funding round.
15% dilution after three funding rounds means the founders still have more than 50% of the shares.
Yeah.
Types of business that gets funded+
And I want to talk more about that in a minute, but I want to go again.
And I’m going to try and cover all the bit of fundamentals.
I feel like the questions that I get a lot are even before that.
I think that there’s so much confusion out there when it comes to funding.
And I think I want to take another, perhaps, misconception—I don’t know.
I would love to clarify this.
It’s about the type of businesses that need to get funded, or should get funded, or can get funding.
Because naturally, investors love tech companies, ones that are scalable, ones that can go, like you said, 10x very quickly, and they can get a positive ROI after their 10 years.
But does that mean that anyone who’s not a tech business is never going to get funded?
What are the typical businesses that do do well?
And which are the ones that don’t necessarily do, or find it harder?
And what can they do?
Because, like you said, for some people that’s the only option right now, to get some funding.
And if they’re in a really difficult industry to grow, what are your recommendations?
So, which are the difficult categories?
Which are the easier ones?
Right, great question.
One of the wonderful things at SeedLegals is to see the unbelievable range of companies.
So, in the Slack channel, as people sign up and start a funding round, I get to see, and I go look at the website.
And it could be people doing a new form of pizza, or bakery, or drones, or deep tech, you know, or something amazing like growing sargassum seaweed to sink to the bottom of the ocean as carbon capture.
So every—I mean, these days there are a lot of AI.
But what I love with SeedLegals is we’re democratizing the ability for founders to fundraise.
And now, the important thing to note is I think there are two classes of things.
One: are you investable in the first place, as opposed to going to the bank?
And number two: what type of investors should you be targeting?
So, let’s talk about investable in the first place.
So, if you go to the bank, they’ll lend you money on the basis that they’re going to make, you know, 5% or 8% interest, which means they have to have like a 98% chance of getting their money back.
Otherwise, it doesn’t make sense.
But your company doesn’t have a 98% chance of success and can’t repay them.
So, investors work on the basis that they’re going to get 10x their money back, but half the companies they invest in are going to go bankrupt.
So, VC funds would look to get to 50x their investment.
They do 20 investments.
Statistically, there’s something called a power law.
And for a VC fund, if they make 10 investments, five of them will lose money, three of them will make a bit of money, and one of them will make 50x and what’s called return the fund.
So, if you approach a VC fund, they’re going to be looking for each company to be a unicorn, or they’re out.
This is important to know because, on the alternative, when you talk to angel investors—what’s an angel investor?
You’re an angel investor.
Anyone with a little bit of money, from like £1,000 upwards, can invest.
And in the UK, if you know about SEIS and EIS tax benefits, this is essential to know as a founder.
So, it means when you talk to an investor, you can tell them, “If you invest £10,000, you can tax deduct £5,000 from your last year’s tax return or this year’s tax return.”
And if the business makes money and you keep your shares for three years, you pay no capital gains tax.
And if the business goes bankrupt, you get to, you know, claim loss relief.
So, SEIS fuels the UK startup ecosystem.
And now you’re going to talk to angel investors, and their investment is de-risked.
Now, for an angel investor—and this is important because once you understand the risk and reward for an investor, then you know who to talk to.
So, imagine you’re investing, you know, five grand in a company.
You might make two or three investments a year.
So, it’s no good to say one in 20 of my investments will be a unicorn or whatever because you’re going to be bored of investing well before that.
You want to have a high chance that they’re going to make even a 5x return.
So, here’s the thing to understand, which is if you’re doing deep tech AI that’s going to need lots of money but could be a unicorn, VCs are a great place to go for funding.
But if you’re doing a new pizza, or drone, or some company that may be not capital intensive, maybe more of a fast-moving consumer good, a new kind of beer, maybe angel investors are the better place to go because you’ve got a high chance of having a moderately growing business.
And there’s nothing wrong with that.
If you dial it right back and you’ve got a cheese shop, you’re selling cheese.
There are a lot of cheese shops.
You go to the bank, you borrow some money, buy some cheese, sell the cheese, make some money, pay back the bank, and you grow your business.
So, once you see your business on the spectrum of steady-state family business through to insane, you know, AI startup, put yourself on that spectrum and then go find the investors that are right for you.
I want to talk numbers because I feel like you mentioned earlier valuation.
How companies get a valuation+
And I talk to startups a lot, and obviously, like you’re saying, you need to have some kind of business activity for people to be able to get funded.
But there are a lot of companies who are looking for funding and they haven’t even started.
For example, valuations. Everyone just seems to have a magical valuation of, sorry, a valuation of like a million pounds, right? That’s just the clean startup valuation.
Are investors not aware that this is somewhat bullshit? Where do these numbers come from? How are valuations actually accurately made?
Obviously, the higher it is, the less you’re giving away in the company, so it makes sense to have a high valuation. But if you’re not doing that much activity, you’ve got this great business idea and you can’t really start it, it’s the chicken-and-egg situation again.
Where does this valuation number come from?
All right, so here’s your 101 on valuations, because the answer is probably not what you’re expecting.
Okay, so you need to value your company when you are raising money for two reasons.
One is when you talk to investors, they go, “What’s the valuation?” because that’s going to affect the amount of equity, and that’s, for you, the amount of equity you’re going to give away, essentially.
So, you have to have a valuation, although you don’t necessarily if you use a SeedFAST, but we’ll come back to that.
So, how do you pick a valuation?
There are a few methods you can use.
You can look at TechCrunch and take at least a zero off the end because those are insane US evaluations.
Or you can go to your accountant if you’ve got one.
Your accountant will go, “Are you making a profit?”
You go, “No.”
“Do you have any revenue?”
You go, “No.”
“Are you losing money?”
“Yes.”
They’re going to go, “Well, why is your valuation not zero? And by the way, I think your business isn’t a going concern. You should shut it immediately.”
So, accountants are useless for valuations because they’re looking at past performance, and you’re looking for future potential.
There are also some websites where you can get a valuation, but to me, those are useless as well because it’s garbage in, garbage out.
You go to a website and they use all sorts of complicated formulas to work out a valuation.
But the problem is you put in some revenue projections.
“In year one, we’ll do a million pounds.”
“In year five, we’re going to do £100 million.”
But this is a bullshit number as well.
So, it’s bullshit in, bullshit out, and investors know this.
So, where does that magical £1 million come from?
The answer actually is, on Seed Legals, over thousands of funding rounds, we’ve seen the formula, which is you dilute—you sell roughly 15% equity each time.
So, 15% means that you take the amount that you’re raising, multiply it by five, and that’s your pre-money valuation.
It means your investors own one in six of the business afterwards—16%.
Fair enough, 15%.
That means that most funding rounds, you might be raising £200,000 at a £1 million valuation.
So, it sounds all very complicated, but actually, once you take a step back and you look at thousands of rounds, you see a pattern.
The pattern in the UK goes something like this:
Founders put some money into the business themselves because no one invests on a PowerPoint.
Then you might go to friends and family and raise £50,000.
Then you might do your classic angel funding round, raising £250,000.
Then you do your classic seed round, raising maybe £800,000.
Then you do a Series A round, raising £3 million to £5 million.
The pattern is each time you’re raising three to five times the amount of the last round, at three to five times the valuation, such that the Anthony Rule is:
After three funding rounds, hopefully you don’t need to raise more. You’re ready to exit, or the business is now profitable.
If you do three funding rounds at 15% dilution, the founders still own 55%, so they still control the business.
Now you see that standard formula.
So, that £250,000 SEIS round—well, money is not what it used to be.
A couple of years ago, it was probably a £1 million valuation.
Now it’s more like £1.5 million, something like that.
The important thing is, if you fit the standard pattern, when you go to any astute serial angel investor, they go, “Oh, I see all these companies. They’re all in these buckets for evaluation.”
If you fit this pattern, there’s no friction.
I either like you, your team, and your mission, or I don’t.
But if you come to them with a valuation that’s a bit like you’re in high school valuation, but you’re still in junior school, they just go, “There’s a mismatch here.”
One common mistake is people have no idea how to do valuations.
They go, “Oh yeah, like £10 million.”
The problem is you go to an investor and they go, “Interesting. Nice pitch deck. What’s the valuation?”
“£10 million.”
They know companies coming to them with a £10 million valuation are doing £1 million a year in revenue.
Then they go, “So, what’s your revenue?”
“Oh, I don’t have any revenue yet.”
“Have you built the product?”
“No.”
They go, “Dude, why are you coming to me with this valuation? Come back later.”
And so, the story of your life is, “Come back later.”
By the way, there’s another problem with picking a high valuation.
Often, crowd investors who aren’t experts at valuations are a bit naïve.
If somebody says the valuation is £10 million, it sounds desirable, so they may invest.
Then the company launches the product, and now they want to raise more money.
But now they’re kind of in high school.
So, they go to VCs for money, and the VC, who knows how to do valuations, goes, “I’m sorry, this £10 million valuation was insanely high. We’ll invest at a £5 million valuation.”
That’s called a down round.
So, your early investors have now essentially lost money because the valuation went down, and they’re going to be pretty unhappy.
So, you want to keep your early investors happy by not picking too high a valuation.
Oh, I love that you pointed that out because I think that’s going to be someone who’s inexperienced with this.
That’s going to be a natural tendency—to do that because you feel like, “Oh, I’m giving away less equity by raising the same amount of money.”
So, they’ll overvalue it.
But it’s great to know the dangers that could happen later.
Obviously, pissing off people who really invested in you early is not a good look.
Exactly.
You brought them on board. They’re taking all the risk.
It comes from a sort of naïvety on founders that they just read TechCrunch and go, “Oh, someone’s valuation was £10 million.”
They just pick a number.
How startups benefit from SeedLegals+
But I would love to now talk specifically about the SeedLegals journey because I think that loads of people would love to know. Say they’ve been listening to this podcast now and they’re like, “Right, I’m convinced. I need to go to SeedLegals. It sounds great. What do I do?”
I feel like a lot of the businesses I’m speaking to who are going through a raise are often mainly service-based businesses or property-based businesses. They’re not necessarily products, which I feel are a little bit different. But, as you said, there are all sorts of different businesses.
Say we’re now a business owner who’s clueless with funding, hence they want the support from SeedLegals, but they don’t have the money for big, giant lawyers. They’re like, “Right, I’m definitely going to join SeedLegals.”
What should they prepare before they join SeedLegals? What would make their journey easier? Should they have all the documents and ideas ready? And then what is that journey like when you start with SeedLegals all the way through?
All right. Cool. Great question.
Usually a couple of founders get together and have an idea. Sometimes they’ve been working on this for a while and now they want to raise investment, but sometimes it’s new.
So, the first step is generally to incorporate your company on Companies House. Once you’ve gone from, “It’s a hobby,” to, “This is a thing,” incorporate. It’s super easy to create a business on Companies House. Make 100 ordinary shares. Don’t try to copy Zuckerberg and make super-voting shares because investors will force you to unwind that.
Then the next step is you probably want to now find investment. To find investment, you need to create a pitch deck. There’s a pitch deck template you can get from SeedLegals, and there are great videos and webinars if you go to the resources section on the art of storytelling.
I’ve done a webinar with the wonderful CLA McMillan. CLA’s an ex-criminal barrister who’s now a pitch deck coach.
How come a criminal barrister became a pitch coach?
Well, she says that in her years of being a criminal barrister, cases were very rarely won or lost on the facts. It was on the story, the art of the story, the art of the pitch. So, she now coaches on that. We did a webinar together.
One of the key things that founders really need to learn is the art and craft of being a founder. This comes well before legal documents because when investors talk to you, if you talk the talk and know what you’re talking about, have sensible valuations, and can answer their questions…
If they say, “Do I get drag-along?” and you go, “Deer in the headlights. What’s drag-along?”
…then you’re at a disadvantage.
But if you go, “Yeah, yeah. Our drag-along is 50%, and we offer standard drag-along and tag-along rights,” then they know that you know what you’re talking about, and they won’t try and screw you.
So, the next step is you’ve got a pitch deck, and you now want to get your SEIS Advance Assurance so you can tell investors they can get their tax benefits, which is the difference between, “I’m in,” and, “Call me when you’ve got your Advance Assurance.”
We help you do that, and something like 60% of all Advance Assurance applications in the world are done through SeedLegals. So, we’re experts at that.
Then you now want to go and find investors.
How do you find investors?
Well, we’ve got resources on that. There are a whole lot of videos. You might use LinkedIn outreach, so you might start messaging people.
Don’t say, “I’m raising £200,000. Guaranteed returns. Can I send you a pitch deck?” because the person will go, “Delete.”
What you want to do is find people. There are some tricks to use.
You may find, for example, other companies like yours that have raised investment. Then you can look on Companies House. You can look at their last confirmation statement, and you’ll see the list of their investors. You might then ping them.
You might say, “Hey, I see you’re passionate about this,” or “You’ve written articles on this,” or “You’ve invested in that. We’re working on the next generation of that,” or “We’ve got an even better no-alcohol beer. I’d love to tell you more. Would you like to know more?”
Something that indicates you’ve done your research. It’s contextual, exactly personalized to that person, and with a message that invites them to want to talk to you.
You should think about investor outreach like a Netflix series. The goal of episode one is to get you to watch episode two. Then you’re in.
If you’re too forward on the first episode, there’s no second episode. It’s a story.
So, all of this is nothing about legal documents. It’s all about the art and craft of being a founder, figuring out the talk, walking the walk, and finding investors.
Now you’ve got investors. You’ve got a potential investor. Now you go, “Great. Can I tempt you to invest £20,000?”
The investor goes, “Sounds great. I’m interested.”
Oh my God. What do I do next?
Yeah. Thank you.
So now, SeedLegals is exactly there.
Once upon a time, people did a funding round. A funding round is like a bus trip. You get all the passengers on the bus—in other words, all the investors—and you say, “I’m raising £250,000.”
Let’s say you’re raising from angel investors, and they might invest £10,000 or £20,000 each. So maybe that’s 20 investors. Maybe you’ve got some larger ones, so it’s fewer. But for an early-stage round in the UK, it’s probably going to be 10 or 20 angel investors.
So now you have to find £250,000, which means that the bus is only going to go in four months’ time once you find these investors.
You’re going to say, “All right, great. Thank you. I’ll put you down for the round, and I’ll call you in a few months’ time.”
But you really want their money right now because you don’t want to wait four months to get the money. You want some money now so you’re going to hire somebody now.
So there’s now a newer construct called the SeedFAST. That’s our industry name for it.
A SeedFAST says, “I will give you money now, and you will give me shares later at a valuation that we decide later.”
SeedFAST is great because it means we don’t need to agree on the valuation now.
Because if you’re the first investor, you might go, “Well, if I’m investing at a £2 million valuation, what happens if other investors don’t agree on £2 million and want £1.5 million? I’m now the only idiot who’s come in sooner.”
So, SeedFAST de-risks it for the investor by saying, “I’m giving you money now, and I will get whatever valuation you agree with the other investors later. But to incentivize me to come in now, you’ll give me a 10% or 20% discount compared to the other investors.”
This we call agile fundraising.
So, you can raise ahead of a funding round or top up a round in addition to doing a funding round.
Agile fundraising has changed everything. Seventy percent of all investment we see on SeedLegals is not in a funding round. It’s ahead of a round with SeedFAST or topping up a round afterwards.
I think the funding round is like a bus trip, and SeedFASTs are like an Uber.
So, we meet, and you go, “Hey Anthony, love what you’re doing. Can I invest?”
I go, “Sure. I will send you a SeedFAST on SeedLegals for £10,000 or £20,000.”
Great.
I’ll go to my mobile phone, create one for you, you can e-sign it, and there’s data to show what the discounts are and so on to offer.
That has transformed fundraising.
There’s an equivalent in the US called a SAFE, which has also transformed fundraising in the US.
So, that’s the way to roll.
Wow. That’s pretty cool. It’s amazing, actually. It’s showing how many ways there are now to get access for both sides—for investors to invest more…
SeedLegals v Law Firms+
…and, obviously, for businesses to get funded.
I have a few questions on the specifics, though, because I feel like SeedLegals helps so many small businesses. To me, it seems like a no-brainer to use, but naturally, to law firms doing this, they see you as an enemy and a threat. They’re naturally going to say things against you guys—that it’s not good enough.
So, the typical things that I would hear from a law firm are that you’re not thorough enough, you’re not going to check things properly, and you’re not going to notice things for the founders. It’s not specific enough, so it’s all generalized.
I’d love for you to address some of those because, obviously, you’ve helped, like you said, 50,000 UK startups, which is nuts, and they all seem to do fine from it.
So, what are those concerns they have, and what can you say about those?
Well, you know, I meet lawyers and they say they train to try and win business from SeedLegals.
But what I like is companies start right at the beginning on SeedLegals, and they don’t make the mistakes that you make without it.
One of the key problems that founders have is they split up. So, you need founder agreements. By showing you the right way to do things, that’s good.
When it comes to standard or bespoke things, the concept of everything needing to be non-standard is insane, and that leads to the insane lawyer fees.
Imagine you go and rent a car. You get out of the airport, and your car’s waiting. If the pedals, the indicators, and the steering wheel are in exactly the same place, you get in and drive.
But if some manufacturer decided to move all the things around, the pedals are no longer there, and it’s insane.
The same goes with fundraising. Investors make investments in a lot of companies, and they want deal documents to be the same. You don’t want each deal to be different. You want it to be the same because the fundamentals are the same.
Actually, there are about a dozen key deal terms that are negotiated.
Does the investor get a board seat?
Obviously, what’s the valuation?
What consent rights does the investor have?
The idea is you’ve got standardized documents that reflect these things you negotiate.
What lawyers do is they give you a Word document with 5,000 words in it. Your natural inclination is to open it in Word and redline it. You’re changing these words, but that means both parties need a lawyer.
We’re in the age of technology and AI.
What you want is to agree between us that you’re going to get a board seat, and I’ll need your consent on a sale of the company, and so on. Then standardized documents are created.
The reality is the 98% risk in a company is not that the Articles of Association have something that you didn’t spot. It’s that the company runs out of money.
People sometimes mistakenly think that the deal documents they get are like the Bible—this tome sent out from heaven that’s going to last forever.
No.
It lasts for like 18 months or six months until your next round, when it gets replaced.
So, this whole concept that things need to be different and bespoke is nonsense. They’re meant to be the same because, imagine all the things you do in your life—you want them to be familiar.
You change your phone. You want it to be similar to the last one.
You go to a different website. You want the buttons to be in the same place.
Likewise, with a legal document, all it is saying is, “You’re going to give me money, and I’m going to give you a return on investment when these things happen.”
It’s got a sensible balance of protections.
Lawyers who want to change it on a case-by-case basis are either old world or jobsworths just trying to make work on a billable hour.
I think it’s ultimately quite simple.
If you’re charging someone by the hour, your incentive is to make more hours.
If you’re charging someone a fixed fee, your goal is to make it simpler.
Most common mistakes+
You mentioned the mistakes that founders make, and that’s obviously what you help minimize, which I love because I do think that, like I said, there are so many myths out there about raising capital that it’s great to have a team to support you.
What are the most common mistakes that founders make that you see? Because, obviously, like you said, you’ve got 50,000 startups. People must make lots of mistakes all the time. What are the biggest ones, and what should founders do to avoid those?
Right. Well, the biggest mistakes—I mean, some of them are around legal matters—but the biggest mistakes are about products.
So, you have this idea. There’s something that’s been bugging you. My bike got stolen. I need a solution for that. Whatever it might be.
“I’m going to make this AI-enabled blockchain bicycle lock with GPS and Wi-Fi,” you know, whatever it is. And you believe that everyone’s going to want it, and you don’t do your research.
So, the number one mistake founders make, in my view—and I made it all the time and continue to do that—is you think the hard thing is building it. But it turns out that, retrospectively, it was pretty easy building it. The hard thing was getting people to want it.
So, you put all this effort in, you raise money, you get people to join you, you build it, and then a year or two later, you wake up in a cold sweat going, “Oh my God, nobody wants this. It was a vanity project.”
So, the number one mistake is not validating it before you build it.
I think of it like this. Once upon a time, it was, “Build it and they will come.” Kind of like this gorgeous building—they built it and then hoped people would come.
Then along came Agile and minimum viable products. So, you would make something simple and hope people used it.
But now you can go further with Lovable and Cursor and AI dev tools, and you can actually make something very simple. You’re probably going to have to throw that code away and recode it, but you can make something very simple that looks like the real thing, and you can test it.
By doing this, even with a weekend’s worth of, you know, vibe coding, you can now show people. If they go, “Don’t know what it is,” or, “Not me,” or, “Actually, I’ve seen three like it,” you realize in no time that you have an uphill battle to try to get people to use it.
But I think you can go one step further. I like the concept of writing the press release, and if no one’s interested in the press release, don’t even build it.
So, imagine you go, “I’m working on a new money-saving app for students that’s going to do something.”
You could spend a lot of time building it. You could spend a little time vibe coding it and hang out at universities and go, “Please try this app and see.”
If people go, “Not really,” you’ve just saved yourself a few years of your life.
Or maybe they go, “This is awesome.”
Or maybe they go, “I don’t understand what these things do.”
Then you come back next weekend with a better, improved version.
But you might even go further and write it up as if it existed and show people. If no one’s going to write or publish your press release, it means it’s missing a stick to stand out from the crowd.
So, the number one problem, I think, is all about product testing and validation before you build it.
Number two is not having a founder agreement.
So, founders get together in a pub.
“Hey, let’s do this.”
“That’s great.”
It’s a hobby, and no one pays much attention to things.
Now you go on your first funding round, and suddenly you’ve got a nominal valuation of £1 million. That means two founders. You may not even have agreed the equity split. Is it 70/30? 50/50?
But now each 10% is worth £100,000.
So, suddenly things got serious.
Now, if you get past that, you’ve got funding, and now you can’t see eye to eye. It’s taking a year or two years. Somebody’s got to pay their rent. Your spouse is going, “Dude, you need to get a proper job.”
One of the founders leaves. Maybe 20% of the time—or more—founders split up.
If the founders don’t have a founder agreement with share vesting that says, “If I leave, I have to give back some of my shares,” they leave with all of their shares, and then the business is uninvestable.
No one invests in a business where half the shares are owned by somebody who’s left.
Worse, if they leave on bad terms, they might say, “I own all this work I’ve done. It’s mine. I take it back.”
So, the company’s screwed.
A founder agreement, which you can do on SeedLegals, is an absolute essential.
It’s got a few provisions. It says, “If I leave, then I have to give back some of my shares.”
It says all the work I put into it belongs to the company.
So, it’s a concept that says the company goes forward and people can come and go.
When people message us on web chat on SeedLegals and say, “Hey, I’ve got a founder dispute. What do I do?”
Our team replies, “Do you have a founder agreement in place?”
If yes, great. Let’s look at what it says and then follow the next steps.
If not, it’s kind of pistols at dawn because it gets acrimonious, and the business often just falls apart.
So, doing that founder agreement, which is free on SeedLegals, is really an essential first step for any business, and investors are going to insist that you have that in place anyway.
Yeah, I can imagine that because they’ve got to obviously understand the stability of the company. They’re definitely going to want that.
Rate of failure+
I would love to also understand failure rates in that sense as well. Like, how many businesses come onto the platform, set themselves a big funding goal, and then just don’t make it? And what are the reasons for not making those goals as well?
Well, it’s a good point. I think there are a couple of parts to that question.
One of them is people might want to raise more than makes sense for that stage of the business.
I think it goes as follows, which is, “Okay, how much money do I need to raise?”
So, you take out a spreadsheet. I do this every few startups. You go, “Well, I need two software developers. I need a designer. I need a product person. I need a data person. Of course, I need sales and the two founders.”
Okay, that’s eight people. It’s, I think, always eight people.
So, let’s say I’m going to work on £50,000 a year. That’s £400,000 a year. I need to raise for 18 months. I need £600,000.
Great. So, £600,000 means a £3 million pre-money valuation, multiplying by five.
Now you go to investors and you say, “I’m looking to raise £600,000 on a £3 million valuation.”
They go, “Awesome. How many users do you have?”
You go, “No, I haven’t built it yet.”
They go, “Well, love what you’re doing. Come back later.”
So, you have to revise it down to probably £250,000 at a £1.5 million valuation.
The first mistake is trying to think you’re going to hire too many people and raise money for that. You probably have to pare it back.
The next problem is, of course, finding investors.
If you want to raise a few hundred thousand, you have to kiss a lot of frogs.
I think founders might give up too easily. The batting average is maybe one in 30 investors, or one in 100 investors you talk to, will invest.
Spray and pray is one technique. It’s much better if you can obviously have more targeted, warm outreach that gets a higher conversion rate.
One common mistake is some investors or advisers say it’s just as easy to raise a big amount as a small amount. You should raise a big amount.
This is the world’s worst advice because all that means is you go, “Great, I’m going to raise £1 million now because some naive idiot adviser told me that,” who’s not part of the journey.
So, you start talking to all these VCs about £5 million or £10 million valuations, and they just ignore you. They look at you like, “Why have you come to university when you’re still at preschool level? Come back later.”
If you think about time and the amount you want to raise, you’d like to raise a big amount on day one, obviously. But you’re going to be kissing a lot of frogs for a long time trying to find that magical set of investors to give you this big amount of money at a big valuation.
Much better, in my view—because your life also has a value—is to raise smaller amounts over time so that you can raise some money to hire a person to do some development and product design, then use that extra product you’ve got to get a higher valuation to raise more.
That’s where SeedFAST and so on come in.
So, instead of going, “I need to raise £500,000,” go, “If you’re in for £20,000, I’ll take it today,” and then use that to grow the business faster.
So helpful. I’m just thinking about this all the way through.
So like you know…
How SeedLegals supports+
Here’s your transcript rewritten into proper sentence format, with timestamps removed, spacing added after every sentence, spelling corrected, and the wording preserved as closely as possible.
Depending on whether they’ve got co-founders—a lot of people do—that’s why they need the founder agreements. Some people are also by themselves. They’re solo founders. But even with co-founders, a lot of them are still going to be inexperienced.
You’ve just given so much great advice so far. What sort of level of support can we expect from SeedLegals? For example, throughout the different stages of the process, founders are going to be making mistakes. They’re going to be, you know, again, like, because obviously I’m guessing you guys don’t look at every single agreement, all the details, and find out if investors are taking advantage of people. There might be situations like this, and they’re going to make big mistakes.
How involved does SeedLegals get, and what support and what level of legal support can we get from you?
Sure. I mean, mostly what people want, by the way, is commercial support. Sometimes it’s psychotherapy support more than legal support.
The idea is you can always message us on web chat, and we’ll get on a Zoom call or whatever. There’s a spectrum. Some founders say, “I don’t need to talk to you. I know exactly what I’m doing. Just point me to the place on the platform to do all the documents I want.” Some people need a lot of help.
The mistake, I think, is people think they need help on the legal documents. But the legal documents reflect what you want to agree to as people in plain English, and you didn’t need a lawyer to draft a Word document. There’s a computer that can do that.
My goal is to help educate founders on what they want to do at each step. All the things we’ve been talking about now are the exact things that a founder needs to know, and none of them would come from a law firm, and none of them would come from a legal document.
Now that you see the path, of course the hard thing is finding investors. Then you want something to show you which things you negotiate.
The short answer to your question is you hit us up on web chat. We may answer directly. There are videos, there’s data, there’s the SeedLegals Term Meter, where over thousands of rounds we’ve shown the data for small, medium, and large rounds, which things to agree to, and which to push back on.
Of course, helping somebody at great length individually—we’d love to do that—but it’s not really scalable. So, how can we take data, make videos to show you in your own time the formula, and then whenever you’ve got questions, we’re here to help with that?
You get an account manager, and our customers tell us, “Hey, I just keep hitting up Andrew at any time of the weekend, and amazingly, he answers and shows me how to do my account.” I’m not suggesting you do that, but the team does that.
So, yeah.
I want to just touch on the bit about PR you mentioned, because you talked about press releases.
The importance of PR+
Here’s your transcript rewritten into proper sentence format, with timestamps removed, spacing added after every sentence, spelling corrected, and the original wording preserved as closely as possible.
How important is press when it comes to raising? Because I feel like I see loads of press releases that are like, “So-and-so raised X amount of money.” You talk about storytelling and how important that is as well.
How important is a good PR and storytelling journey to getting investment and the whole investment process?
I think it’s essential, but it needs to be correctly targeted.
Of course, after you’ve fundraised, having TechCrunch run a story that you’ve raised money is nice, but actually almost useless. The thing is, your customers are probably not reading TechCrunch. Right? You sell bicycles. People who read TechCrunch are VCs in the US. There’s no correlation.
So, you may get some vanity from that PR, but it’s not doing anything for your sales. Worse, it may lead to this high expectation. “So-and-so raised £20 million. That’s awesome.” Then later on, it turns out your investors all think that everyone in the world is using your service, when actually no one in the world knows about it except them.
So, PR can be negative.
What you do want, of course, is for customers to know about you, and you want investors to think that customers know about you. You want to do that before the raise so that investors see you’re everywhere.
I like the story of Napoleon. Supposedly, Napoleon was outnumbered by a much larger enemy army. What he did was send some soldiers up into the hills at night, and they lit fires. The enemy thought, “Oh my God, we’re surrounded.” It was only like a dozen people in a bunch of hills.
Can you use PR, content marketing, blog posts, LinkedIn posts, and more to appear larger than you are? Because an investor is obviously going to want to do some Googling to find out, “Okay, they say they’re going to change the world. Has anyone ever heard of them?”
If they Google you and your website doesn’t even come up because you haven’t optimized it for SEO, and there are no other articles, you’re obviously invisible. So, you’ve got a mountain to climb.
But if an investor Googles you and they see all these LinkedIn posts, magazines, publications that have your articles, and your website is filled with content, they go, “Amazing. You’re everywhere.”
So, you want to be bigger than you really are. You can do that by paying people lots of money, or you can do that by writing content.
That’s how I got started writing content. There are hundreds of articles on the SeedLegals site and videos done by me. I did it for three reasons.
One, I genuinely love helping people and sharing experience.
Number two, it means that when people ask me questions, I’ve got a scalable way of answering. “Hey, here’s a video I did on that.”
And number three, it’s just great content and great SEO.
Now, if people search for SEIS, we rank higher than HMRC. Yes, great. That’s the holy grail.
So, write content. Get your team to write content.
One of my SeedLegals customers makes green tea. I love green tea, so I went to their website. They had gorgeous pictures of green tea, but I was kind of disappointed.
They could have had articles on the ideal water temperature. Should I put cold water into the hot water first? How is this tea made? What’s the difference between first flush and second flush? Whatever it is.
Had they created all of this content, firstly, it would have improved their SEO. Secondly, I would have seen them as thought leaders and trustworthy. Thirdly, I would have spent more time on their website while browsing and reading those articles, and they might have converted me into a customer.
Writing content is free. It takes time, but it’s immensely valuable.
It also gets you to construct a story that makes sense for your users. If I can’t write an article about how some SeedLegals product is going to help you, I probably shouldn’t build that product.
So, content marketing, as it may be called, is step one.
Step two, if you can, is PR—getting other people to start carrying these stories.
But a lot of PR is simply getting websites to run press releases. Nobody actually reads them except Google search bots and so on. So, that’s not really useful.
What you definitely want is that when investors search for you, they start finding you everywhere.
Yeah, and I think that’s just good standard practice when it comes to marketing in general.
Should you quit your job?+
Here’s your transcript rewritten into proper sentence format, with timestamps removed, spacing added after every sentence, spelling corrected, and the original wording preserved as closely as possible.
But it also leads me to think about how much time that takes, right? So, all of what you’re saying is that you’re constantly making content. You have to be on different platforms. You have to be doing all this sort of stuff.
Now, I see a lot of content where people are talking to people on the street, saying, “You must quit your job, follow your dream, go all in.” Because if they’re just doing it as a side hustle at the moment, they’re employed, but they’re kind of doing it on the side, they’re not dedicating all their time to it, so they’re never going to be successful.
What are your thoughts on this trend? Because obviously, do you think that everyone is meant to be an entrepreneur? You must see a lot of failed businesses doing what you do, and I would love to hear your thoughts on how many businesses you’ve seen and whether people should even do that sort of thing.
So that’s the big, big question, right? Should you even give up your day job?
I read some statistics saying something like 27% of school leavers want to build a startup, and that’s up from around 2.7% a couple of decades ago.
So the question is, are 27% of people the right mindset to be founders?
When I see things like COVID, Brexit, or some war somewhere, and people saying, “Well, I’m worried. I’m not sure how things will change. There’s indecision. I should wait,” you’re not right to be a founder.
A founder would be thinking, “All things are an opportunity.”
To me, the attributes of a founder are that you love taking risks and you love making decisions, because failure to make a decision is death for a startup.
You might ask, “Should we launch in this territory?” Well, there’s no perfect answer.
If you’re in a large company and a question comes up, you can ask others. You can form a group, a committee, and reach a decision.
As a founder, you kind of have to make the decision yourself, maybe with your co-founder.
“Yes, we’ll do it.”
“No, we won’t.”
If you say yes to everything, you’re going to spread yourself too thin.
If you say no to everything because everything is a risk, you’ll never have a business. You’ll never start anything.
So you should look within and ask yourself, “Do I love making decisions? Do I enjoy a certain level of risk?”
I also think that as an employee, if you don’t like what you’re doing, you can quit and do something else.
If you’re a founder, I think it’s like having kids. I don’t have kids, but if you do, you can’t just say, “They’re two years old. I’m a bit bored. Can I give them back, please?” That’s just not an option.
You’ve created this company. You’ve taken investor money. You’ve convinced people to join you.
You have to do everything you can to make it a success.
You’ve got the weight of the world on your shoulders, and you have to make decisions when you don’t know the answer.
You’ve built the product, but you don’t have many users.
So what do you do?
Do you add more features?
Is it better PR?
Is it better marketing?
Do you update the website?
Do you get on calls with customers?
If you don’t like making those decisions, don’t be a founder.
If you love making those decisions, or you learn to love making them, then being a founder is probably for you.
So if you have a day job, how might you make that step?
One way is the “mind the gap” moment—giving up your day job to become a founder.
Remember that founders put a median of £26,000 of their own money into the business.
So unless you’ve got some capital to fund it yourself for a while and not be paid for maybe a year or more, then you’re not financially ready to do it.
You need to put some money away first.
That’s important because, at some point, your spouse starts saying, “How long is this going to go on before you start getting paid?”
Maybe you earned a decent salary as an employee at a large company, but you’re probably going to earn around £30,000 initially as a founder from your first funding round until you get a bit further along.
So being somewhat financially independent is also important.
But it really comes down to mindset.
Being a founder isn’t for everyone.
You could be an employee at an early-stage company instead.
Maybe you become the founding CTO, a tech lead, or join an early-stage startup.
Then you’ll find out whether you thrive in that level of chaos where anything can happen and you can do everything without committee meetings.
If that’s for you, great.
If you prefer the comfort of a larger organization, then you can always go back to that.
I’m so glad you said all that because I just feel like entrepreneurship is really glamorized at the moment.
People make it look like they’re having the best lives. They’re raising money, and people see it as free money a lot of the time.
I think that’s encouraging people to jump into it unprepared, and mentally unprepared as well, and it can take a real toll.
So I think a little dose of reality—hence the no-BS version of what it is—is necessary.
It’s not about being negative. It’s about preparing people for what’s to come because it’s going to be hard work, right?
Exactly. Exactly.
Final piece of advice+
Here’s your transcript rewritten into proper sentence format, with timestamps removed, spacing added after every sentence, spelling corrected, and the original wording preserved as closely as possible.
So, I just want to say a massive thank you for this. I feel like you’ve dropped so many amazing points here today.
I don’t know if you wanted to finish off by saying, if anyone’s going for a funding round right now, you’ve obviously given so many pieces of advice. Is there anything that hasn’t been said? What would you say to anyone going for, or thinking about going for, funding?
Build a product that people want and solve a real problem.
Because I think you see lots of AI companies these days, and they’re like, “AI for this” and “AI for that.”
Actually, the one thing I didn’t mention, which is maybe the number three mistake people make, is that if you look at their website, it says what they do rather than why anyone wants it.
When I talk to a founder, they passionately explain, “Modern dialysis machine,” or something that’s going to change medical care or reduce NHS waiting queues, and you go, “That’s amazing.”
Then you look at the website, and it just says, “AI blockchain something solving distributed logistics,” and it’s all mumbo jumbo.
You want your website to clearly explain, “You’ve got this problem. We’ve got this solution.”
If you can’t get it into that form, you have to keep iterating.
Build something that is genuinely solving a problem for people rather than just “AI for X.”
Yeah, so start with why, as usual. I feel like that’s what it is.
It’s great. Thank you so much for today.
Thank you.
It’s been amazing.
Thanks.
Meet the guest
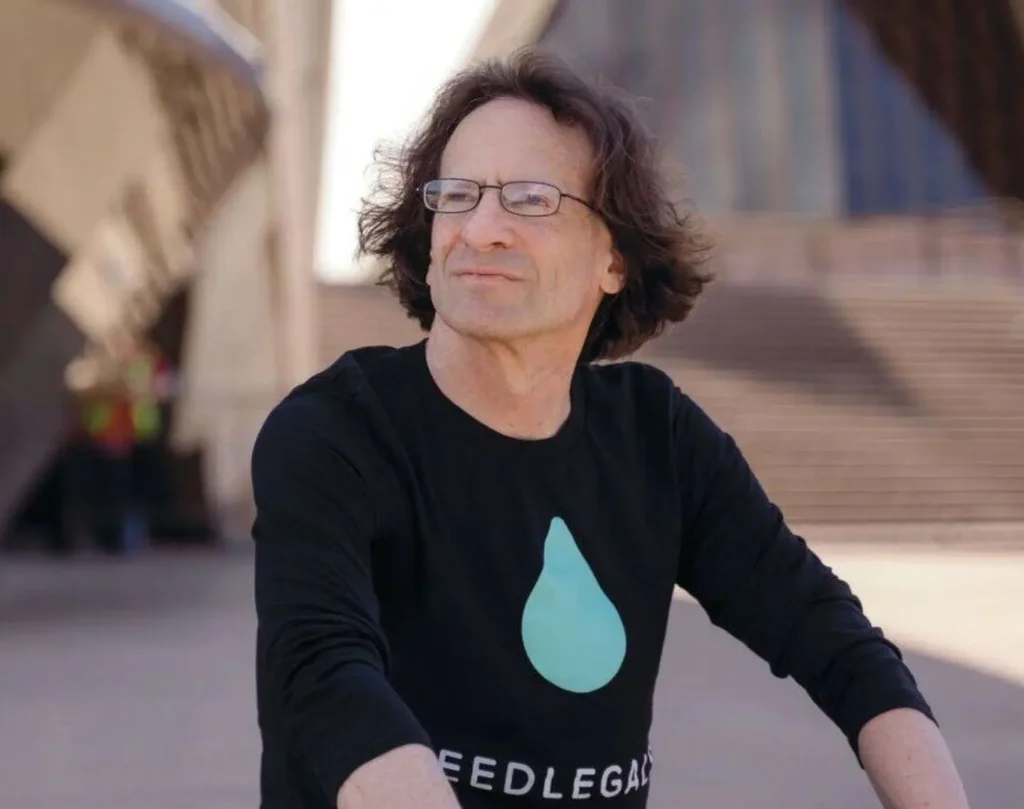
Anthony Rose
Anthony Rose is the founder and CEO of SeedLegals – THE platform to join as a startup looking to raise capital. He’s the man behind the launch of BBC iPlayer, but as a serial entrepreneur at heart, he created a solution to the problems he found frustrating as a founder. He’s helped over 50,000 startups get funded and has completely changed the way legal agreements are handled in startups. Anthony’s Socials